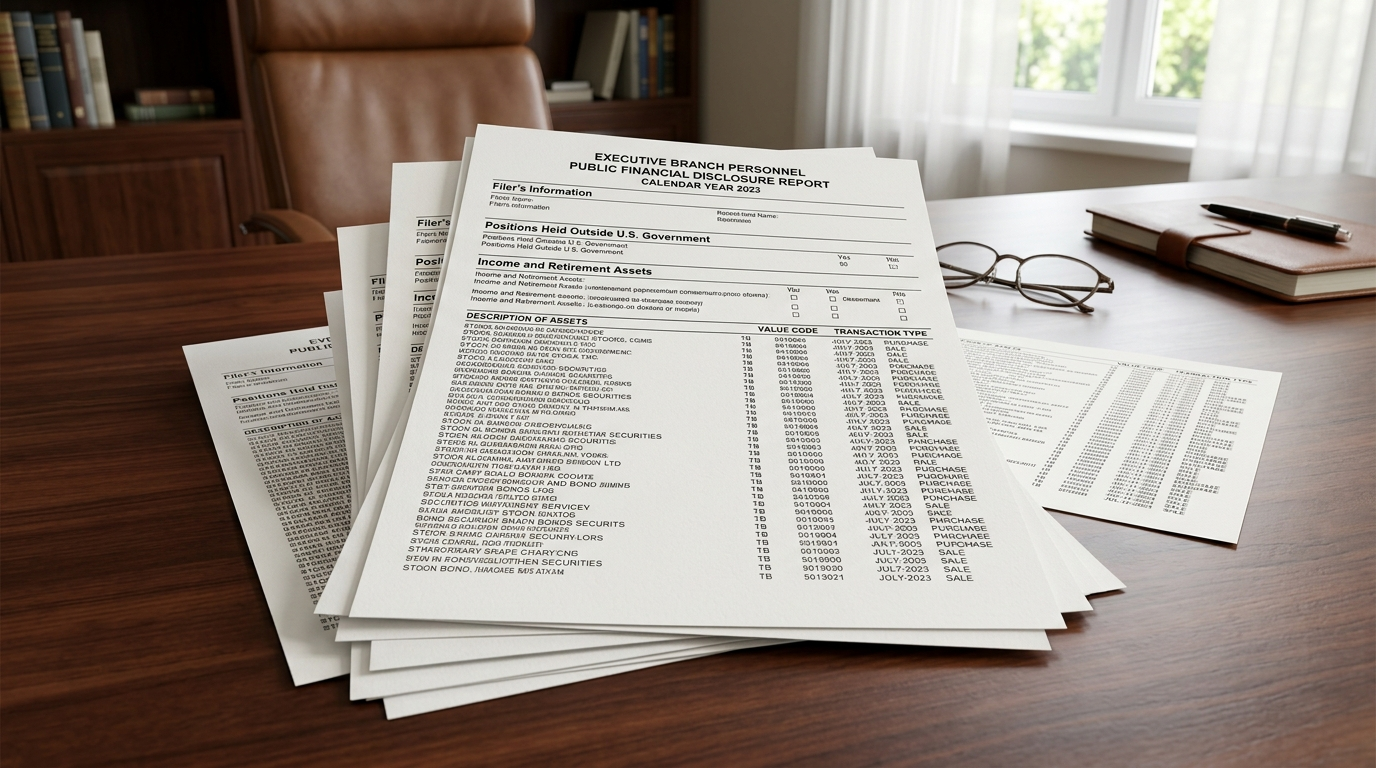
President Donald Trump’s money managers executed 1,152 trades on his behalf in July, according to a financial disclosure released Tuesday.
The total stands out both against the activity reported by previous presidents and the usual pace of active investors. It also renews questions about transparency, oversight, and how presidential assets are managed while a president holds office.
A Striking Volume of Transactions
The disclosure indicates an average of more than 37 trades for every calendar day in July. The actual pace on trading days would have been higher.
Trump’s money managers made “1,152 trades on his behalf in July alone,” according to the disclosure.
Trade volume does not show whether the transactions produced gains or losses. It also does not establish wrongdoing or prove that Trump directed individual decisions.
The managers’ role is therefore an important distinction. Professional advisers often buy and sell securities for clients under an agreed investment plan. The available information does not explain the strategy behind each transaction.
Still, 1,152 trades in one month would require close review to understand the assets involved and the timing of the activity. Key details include the type of securities, transaction values, and whether trades were purchases or sales.
Why Presidential Finances Receive Scrutiny
Presidents face financial disclosure rules intended to reveal assets, income, liabilities, and certain transactions. These filings help the public assess possible conflicts between official duties and private wealth.
Such disclosures do not always provide the precision found in brokerage statements. Transaction values may appear within ranges rather than as exact figures. That can limit estimates of total money moved or the financial result.
The reported activity is described as unusually high compared with Trump’s predecessors. However, the information provided does not include trade totals for earlier presidents. A direct historical comparison would require filings prepared under similar rules and time periods.
The central issues for reviewers include:
- Whether the assets could be affected by federal policy decisions.
- How much control Trump retained over investment choices.
- Whether managers operated independently under written instructions.
- Whether all required transactions were disclosed on time.
Volume Alone Does Not Settle Conflict Questions
A large transaction count can result from several strategies. Managers may rebalance holdings, adjust risk, respond to market changes, or divide orders into smaller trades.
For that reason, the number alone offers only a partial picture. A stronger assessment would compare trade dates with policy announcements and identify companies or sectors involved.
Independence also matters. If advisers had full authority, the activity may reflect routine portfolio management rather than presidential involvement. If Trump approved specific trades, the questions about potential conflicts would be sharper.
The filing’s most immediate finding is clear: 1,152 transactions in a single month represents an exceptional level of activity for a sitting president’s disclosed finances. Yet the trade count is a starting point, not a conclusion.
Further review will depend on the disclosure’s underlying details and any later amendments. Regulators, ethics specialists, and the public will be watching for evidence about who controlled the decisions, what was traded, and whether federal actions touched those investments.