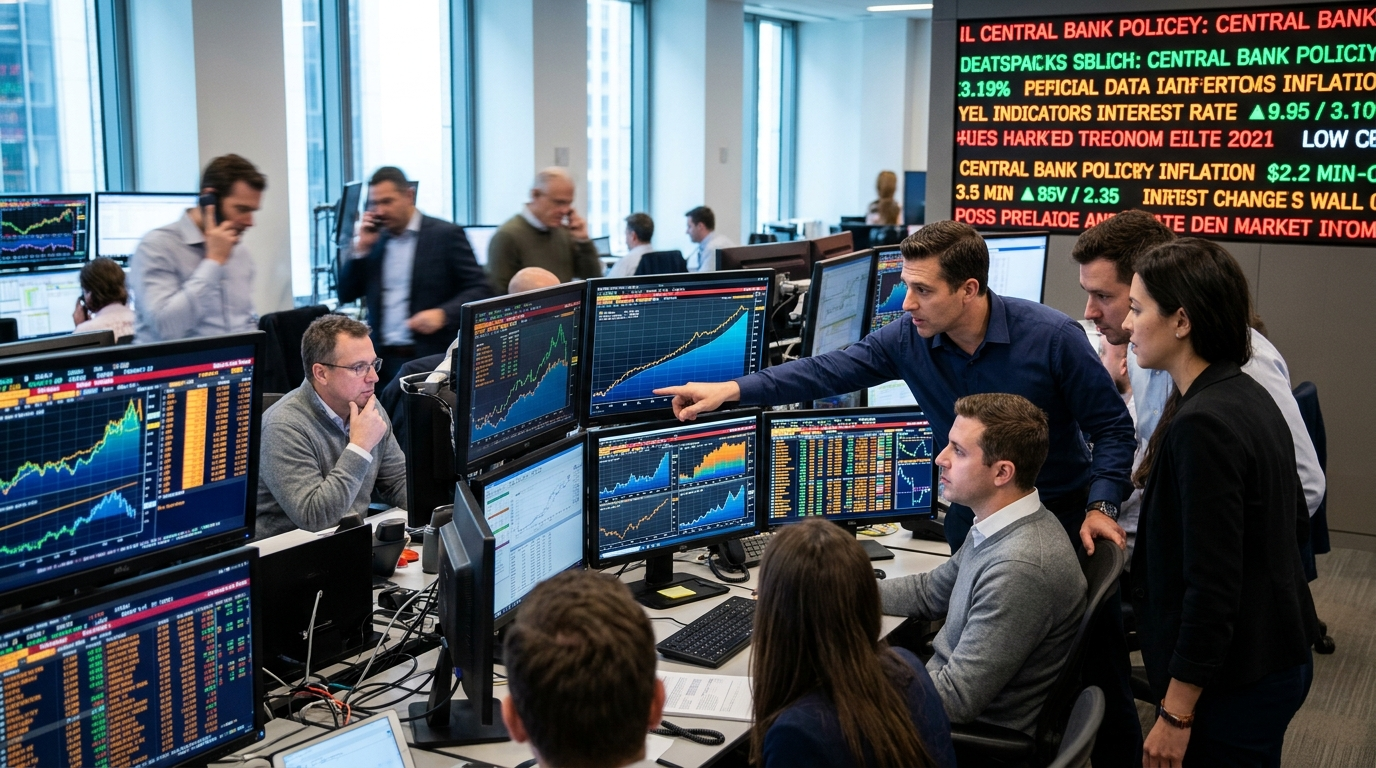
Bond markets may offer the clearest explanation for an unspecified financial development, according to a brief statement directing attention to debt trading.
“To see why, look to the bond markets.”
The statement does not identify the event, policy decision, or market shift under review. It also provides no date, location, data, or named speaker. That missing context prevents a firm conclusion about what bond prices are meant to explain.
What Bond Markets Can Reveal
Bonds are loans made to governments or companies. Their prices and yields change as investors assess inflation, interest rates, economic growth, and repayment risk.
Bond prices and yields usually move in opposite directions. When investors sell bonds, prices tend to fall and yields rise. Strong demand often pushes prices higher and yields lower.
Analysts often study government bonds because they influence borrowing costs across an economy. Changes in those yields can affect mortgages, business loans, currencies, and stock valuations.
Several signals may explain why an observer would direct attention to bonds:
- Rising yields can reflect expectations of higher inflation or interest rates.
- Falling yields can signal weaker growth forecasts or demand for safer assets.
- Wider corporate credit spreads can suggest concern about defaults.
- An inverted yield curve can indicate expectations of slower economic activity.
Interpretation Requires More Evidence
No single bond-market move has only one cause. A jump in yields could reflect stronger growth forecasts, persistent inflation, heavy government borrowing, or reduced investor demand.
Likewise, falling yields may point to lower inflation expectations. They may also reflect fear, as investors move money from riskier assets into government debt.
The maturity of the bond matters as well. Short-term yields often respond closely to central bank policy. Longer-term yields tend to reflect views on inflation, growth, and fiscal conditions over many years.
That distinction is important because markets can send mixed messages. Short-term yields may rise after a rate increase while long-term yields fall on concerns that tighter policy will slow the economy.
Questions That Remain Unanswered
A reliable assessment would require the specific bond market, time period, and price movement being cited. It would also need the event that the bond data is supposed to explain.
Useful evidence could include government bond yields, inflation-linked securities, corporate borrowing spreads, trading volumes, and changes in the yield curve. Comparisons with earlier periods would help separate a lasting trend from daily volatility.
The central claim is clear: bond trading contains an important clue. Yet the available statement does not establish what happened or why. Readers should treat it as a direction for further analysis, not as proof of a particular economic conclusion.
The next step is to identify the relevant market data and test competing explanations. Until then, the bond-market reference offers a useful starting point but no final answer.