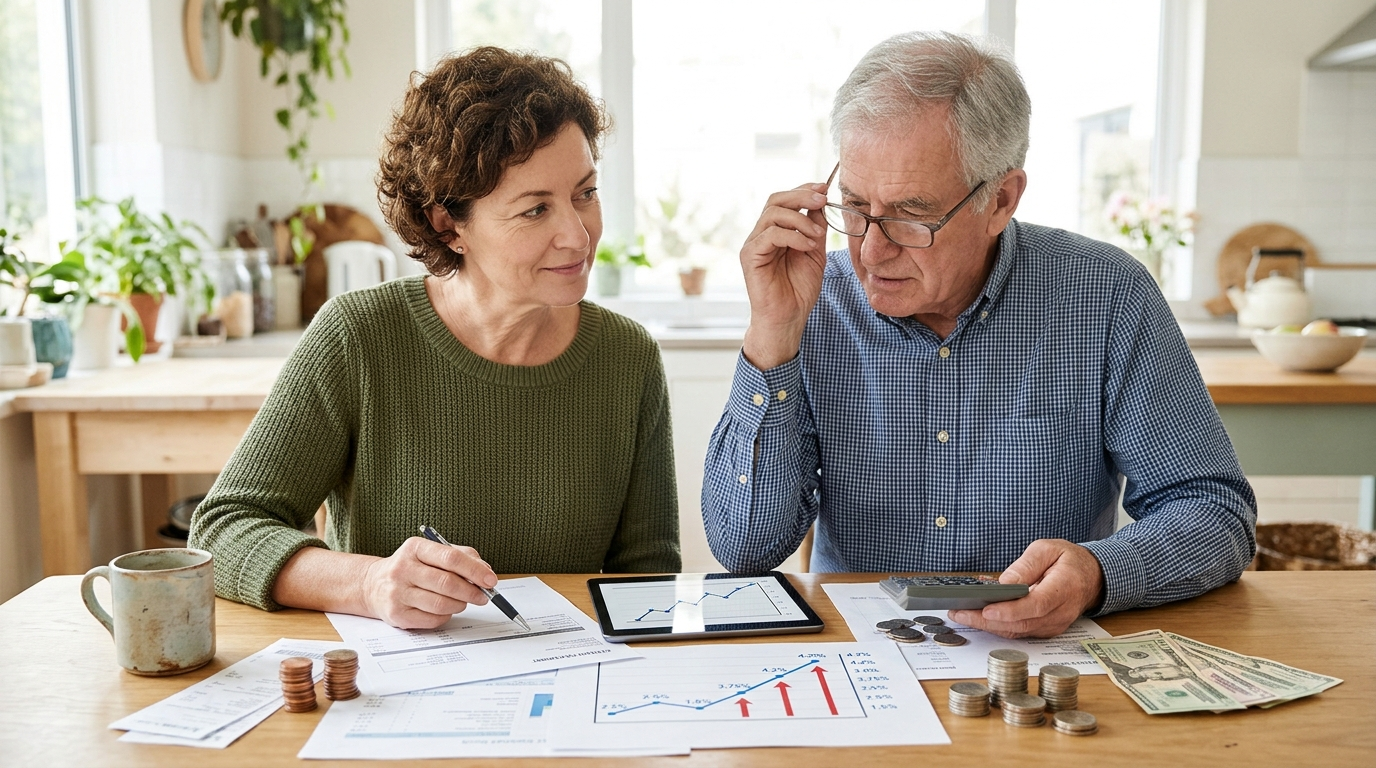
Interest rates rose last month for the first time in three years, increasing pressure on borrowers while offering possible gains for savers.
The increase marks a shift in monetary policy after a long period without a rate rise. The size of the adjustment and the authority responsible were not specified. However, the change could affect household budgets, business investment, savings returns, and the wider economy.
“Interest rates, which impact borrowing costs and savings, were raised last month for the first time in three years.”
Borrowers Face Higher Costs
Interest rates influence how much consumers and businesses pay to borrow money. A higher benchmark rate can feed into mortgages, personal loans, credit cards, and business financing.
The impact will vary by contract. Borrowers with variable-rate debt may see costs rise sooner. Those with fixed-rate loans may be protected until they refinance or reach the end of an agreed term.
For households, higher monthly payments can reduce money available for food, transport, and other purchases. That can weaken consumer spending, which supports many parts of the economy.
Businesses may also review expansion plans. More expensive credit can make new equipment, property, hiring, and inventory harder to finance. Smaller companies may be more exposed because they often have fewer funding choices.
Savers Could Receive Better Returns
The increase may benefit people who hold money in savings accounts or similar products. Banks can respond to higher rates by paying customers more on their deposits.
Those gains are not automatic. Financial institutions decide how quickly, and how fully, to pass rate increases to savers. Customers may need to compare accounts to find improved returns.

The practical effects are likely to include:
- Higher repayments on some variable-rate loans.
- More expensive new mortgages and business credit.
- Potentially better interest payments for savers.
- Lower demand for large purchases financed through debt.
A Turning Point After Three Years
The three-year gap makes the decision important. A first increase after an extended pause can signal concern about inflation or a desire to slow demand. It may also show that policymakers believe the economy can withstand higher financing costs.
Rate increases are often intended to limit price growth by discouraging borrowing and spending. Yet the policy carries risks. If rates rise too quickly, economic activity can weaken. If they remain too low, inflation may stay elevated and reduce purchasing power.
The balance is difficult because rate decisions take time to affect the economy. Existing loans may not reset immediately, while businesses can delay changes to investment and staffing.
Future Decisions Will Shape the Impact
Attention will now turn to whether last month’s increase was a single adjustment or the start of a longer cycle. Future action will likely depend on inflation, employment, consumer demand, and economic growth.
Borrowers may wish to review whether their debts carry fixed or variable rates. Savers can examine whether their bank has increased deposit returns. Businesses may need to test budgets against higher financing costs.
The rate rise represents a clear policy change after three years. Its full effect will depend on how lenders respond and whether further increases follow. The next policy decisions will show whether officials view the move as sufficient or see a need for tighter financial conditions.