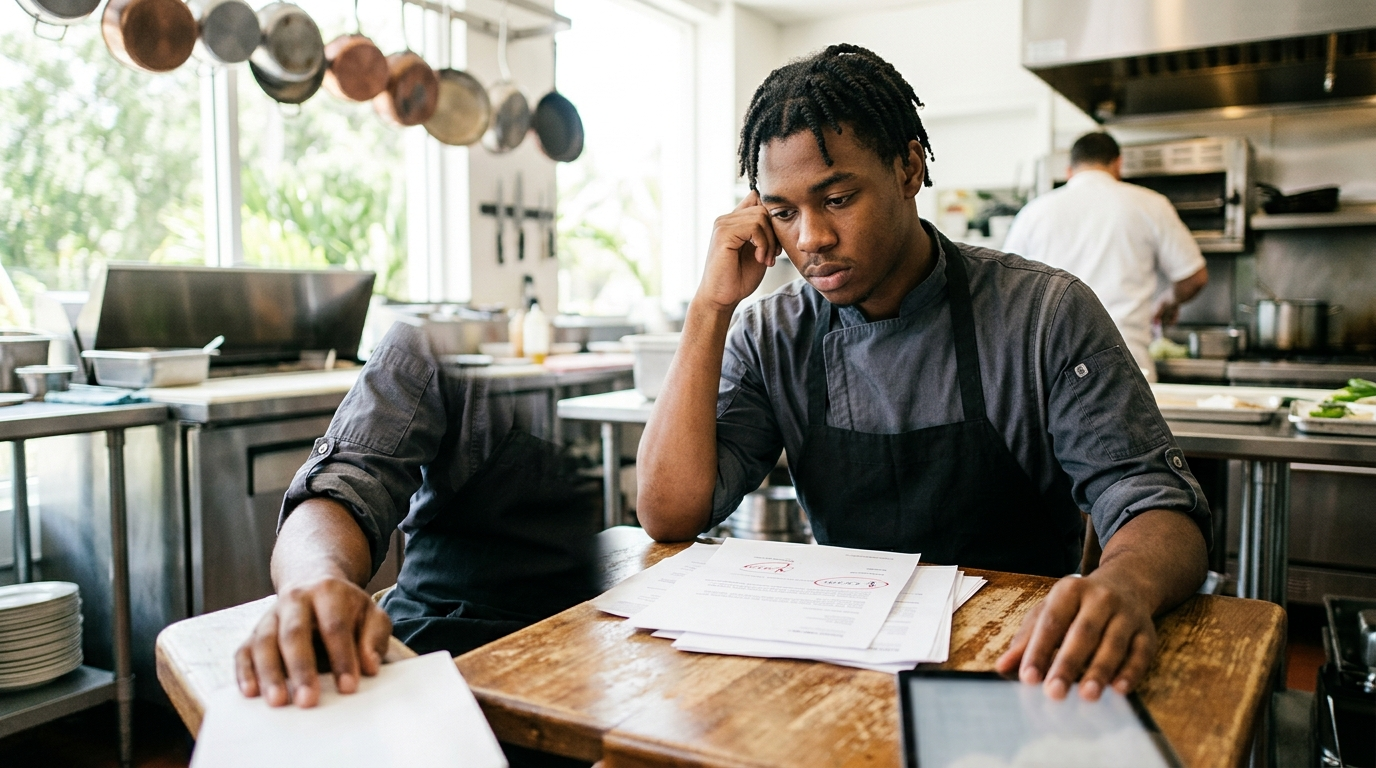
A sharp insurance premium increase has left 21-year-old Florida chef Elijah Button without Affordable Care Act health coverage, exposing the fragile math facing young workers.
Button’s case centers on a simple problem with serious consequences. When the price of his plan rose, he lost the coverage. The available account does not state the size of the increase, his income, or whether he received financial aid.
Those missing details limit any judgment about who was responsible. Still, his experience shows how quickly a monthly price change can push health insurance out of reach.
A Costly Gap for a Young Worker
Restaurant work can come with uneven hours, variable pay, and limited access to job-based benefits. For a 21-year-old chef, even a modest premium increase may compete with rent, food, transportation, and other basic costs.
Losing insurance does not end the need for medical care. Instead, it shifts more financial risk onto the patient. A routine visit may be delayed, while an emergency can produce a bill that follows a worker for years.
Button’s occupation also adds practical concerns. Commercial kitchens involve heat, knives, slippery floors, and long shifts. Health coverage cannot prevent an injury, but it can affect how quickly and affordably someone receives care.
How Marketplace Coverage Works
The Affordable Care Act created insurance marketplaces for people who do not receive suitable coverage through an employer or another public program. Eligible households may receive tax credits that lower monthly premiums.
The final price can change for several reasons. Insurers may adjust rates, available plans may change, and a household’s expected income can alter its subsidy. Administrative deadlines can also affect whether coverage remains active.

Key questions in Button’s case remain unanswered:
- How much did his monthly premium increase?
- Was he receiving a premium tax credit?
- Did an income estimate or plan change affect the price?
- Was the policy canceled, or did he drop it because of cost?
Those distinctions matter. A policy ending after missed payments is different from an insurer withdrawing a plan. Both can leave a person uninsured, but they call for different remedies.
A Broader Affordability Test
Supporters of the ACA argue that its marketplaces give workers an option outside employer insurance. Critics point to premiums, deductibles, and complicated enrollment rules as evidence that access on paper does not always mean affordable care.
Button’s situation touches both arguments. The marketplace offered a route to insurance, yet a higher price appears to have made that route unsustainable. That is the policy tension in miniature, with a kitchen worker stuck holding the bill.
Possible next steps could include reviewing marketplace eligibility, checking whether updated income information changes available aid, or seeking another qualifying plan. The limited account does not say whether Button has pursued those options.
His case is also a warning for other policyholders. Renewal notices deserve close attention because premiums, subsidies, and out-of-pocket costs can shift from one plan year to the next. Comparing the full cost, not just the monthly charge, may prevent an unpleasant surprise.
For Button, the immediate issue is personal: finding an affordable way back into coverage. For policymakers, it is a wider test of whether insurance remains usable after prices rise. The next key facts will be the size of his premium hike, the reason coverage ended, and whether financial help can restore it.