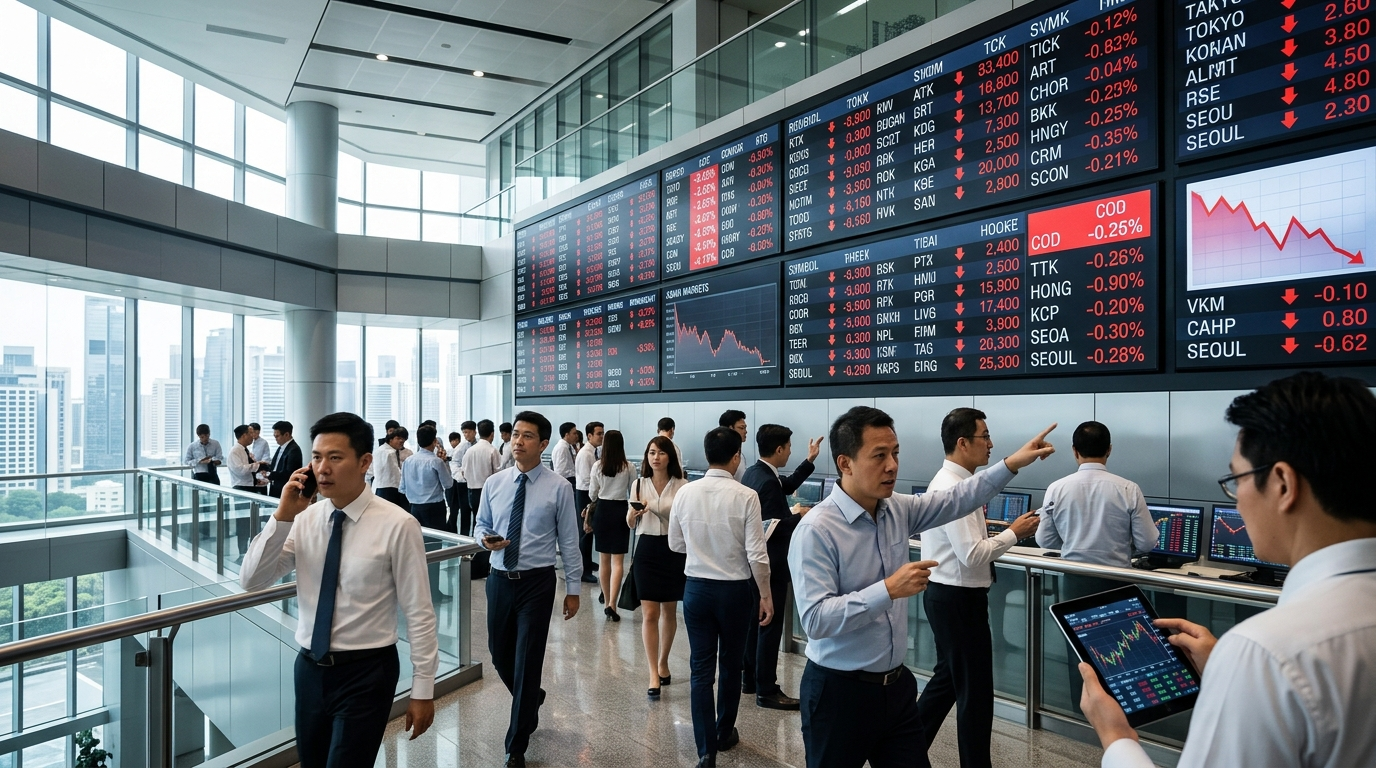
Asian stock markets were set to open lower after Wall Street fell, as rising oil prices and government bond yields renewed concerns about inflation and borrowing costs.
Investors were also questioning whether the US Treasury can keep yields contained for long. Its efforts may provide short-term relief, but markets appear doubtful that lower borrowing costs can be sustained.
Wall Street Weakness Spreads to Asia
Declines in US equities often shape trading across Asia. Lower share prices on Wall Street can reduce risk-taking in markets including Japan, South Korea, Hong Kong and Australia.
The expected retreat reflects pressure from two major forces. Oil prices are climbing, while benchmark bond yields are moving higher. Together, they can weaken the outlook for company profits and economic growth.
Higher yields also make government debt more attractive compared with stocks. That can prompt investors to shift money away from equities, especially shares carrying high valuations.
Oil Adds to Inflation Concerns
Rising crude prices can raise costs for transport, manufacturing and energy-intensive industries. Companies may absorb those expenses, reducing profit margins, or pass them to customers through higher prices.
Asia is particularly sensitive because many of its largest economies import substantial amounts of energy. A sustained oil increase can weaken trade balances and place pressure on local currencies.
The market effects may differ by industry:
- Airlines and shipping companies face higher fuel expenses.
- Manufacturers may pay more for production and distribution.
- Energy producers could benefit from stronger commodity prices.
- Consumers may have less money available for other purchases.
These pressures can complicate central bank decisions. Policymakers must weigh inflation risks against the danger that restrictive interest rates will slow demand too sharply.
Treasury Measures Face Market Doubts
The US Treasury can influence borrowing conditions through decisions about the timing, size and maturity of government debt sales. Adjusting those plans may reduce pressure in parts of the bond market.
However, investors appear to view such relief as potentially temporary. Bond yields are also shaped by inflation expectations, Federal Reserve policy and the volume of federal borrowing.
Investors were betting that the Treasury’s efforts to contain borrowing costs may offer only a temporary reprieve.
If yields remain elevated, financing could stay expensive for households, businesses and governments. Mortgage rates, corporate debt costs and equity valuations may all feel the effect.
Key Signals for the Next Session
Market participants will watch whether Asian losses remain concentrated in technology and consumer shares or spread across the region. Currency movements will also matter, particularly if higher US yields support the dollar.
Another focus will be the relationship between oil and bonds. A continued rise in both could reinforce inflation concerns and limit expectations for interest-rate cuts.
The expected Asian decline shows how quickly pressure in US markets can travel through global trading. The next test is whether Treasury actions calm bond investors or merely delay another rise in yields. Oil prices, debt sales and central bank signals will shape whether the pullback remains contained or develops into a longer period of market weakness.