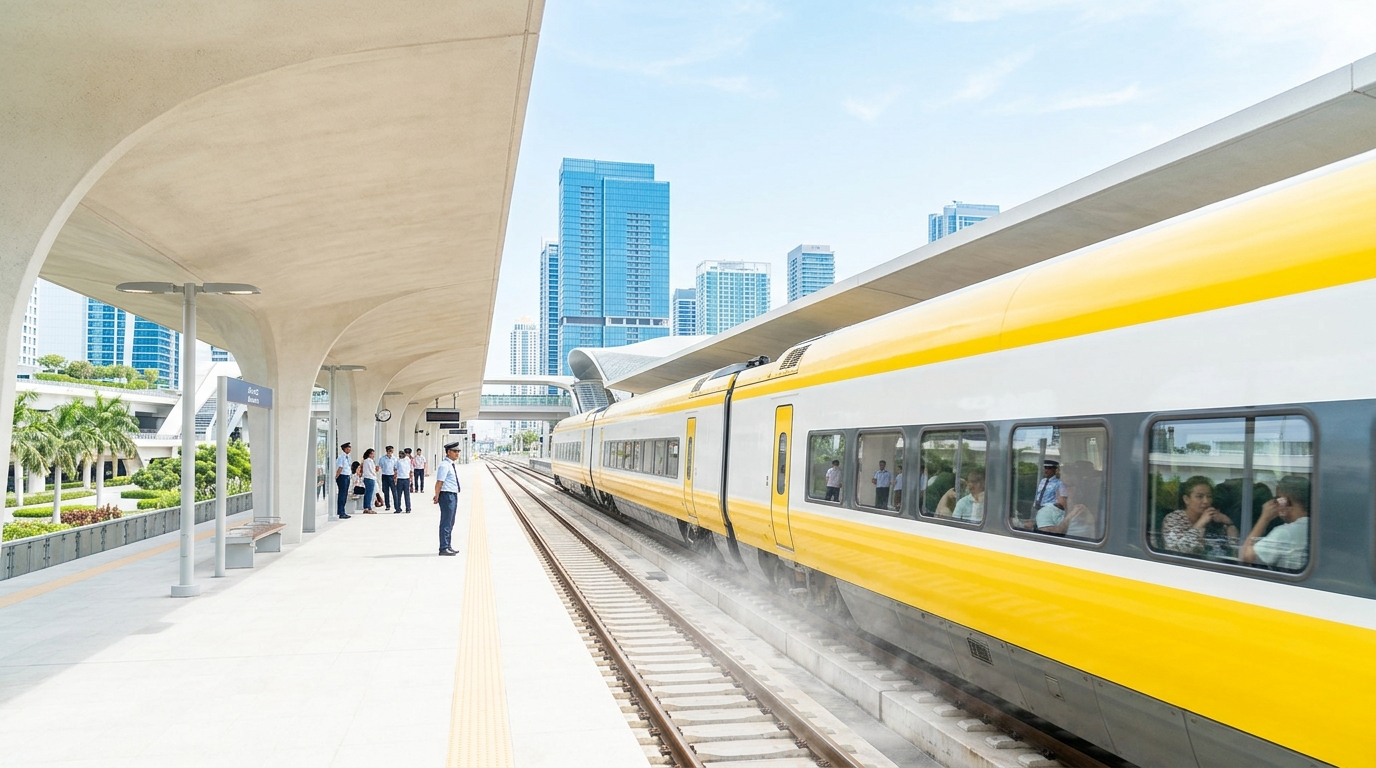
Florida’s Brightline has reached a restructuring agreement that will inject $490 million into the privately operated passenger rail service while reducing its debt burden.
Assured Guaranty announced the financing commitments on Friday. The package includes $350 million in new junior debt and another $140 million in capital. Full terms of the second commitment were not disclosed in the announcement.
The agreement gives Brightline more funding as it operates its Florida rail network and manages the high costs tied to passenger service. It also signals continued support from financial partners despite pressure on the company’s balance sheet.
New Capital Comes With Junior Debt
Most of the new financing will come through junior debt. Such debt typically ranks behind senior obligations for repayment if a borrower enters financial distress.
That lower priority can mean greater risk for creditors. It can also give a company more flexibility than senior financing, depending on the final conditions.
The financing commitments include “$350 million of new junior debt” and $140 million in additional capital, according to Assured Guaranty.
The restructuring is also intended to lower Brightline’s existing debt. However, the announcement did not provide the size of that reduction, the company’s revised debt total, or the financing costs.
Those missing details will matter when investors assess whether the deal provides lasting financial relief. Interest rates, repayment dates, and creditor priority can shape how much room Brightline gains from the transaction.
Private Rail Requires Heavy Investment
Brightline differs from many passenger rail systems because it is privately operated. Rail businesses require major spending on tracks, stations, trains, safety systems, and daily service.
Those fixed costs remain significant even when ridership or ticket revenue falls short of expectations. New routes can increase passenger volume, but they also require more capital and add operating expenses.
The restructuring addresses two related needs:
- Providing cash to support operations and other corporate needs.
- Reducing debt pressure that could limit future spending.
The $490 million commitment may improve near-term liquidity. Yet $350 million of the total is new borrowing, meaning Brightline will still need enough revenue to meet future obligations.
What the Agreement Means for Brightline
For passengers, the immediate effect is likely to be limited. The disclosed terms did not identify fare changes, schedule revisions, route adjustments, or service reductions.
The larger effect is financial. A stronger cash position could help Brightline maintain service and manage expenses. Lower existing debt could also ease repayment demands, though the value of that relief depends on the final structure.
Assured Guaranty’s role adds weight to the announcement because the company is a financial guarantor with exposure to debt markets. Its disclosure confirms that firm financing commitments are part of the agreement, rather than only a proposed fundraising target.
Still, the limited public details leave key questions unanswered. Investors and transportation officials will watch for final documents explaining how much debt will be retired, what interest Brightline will pay, and when the new obligations mature.
The restructuring gives Brightline a sizable capital injection at an important time for the private rail operator. Its long-term impact will depend on whether ridership and revenue can support operations while the company manages its revised debt load.